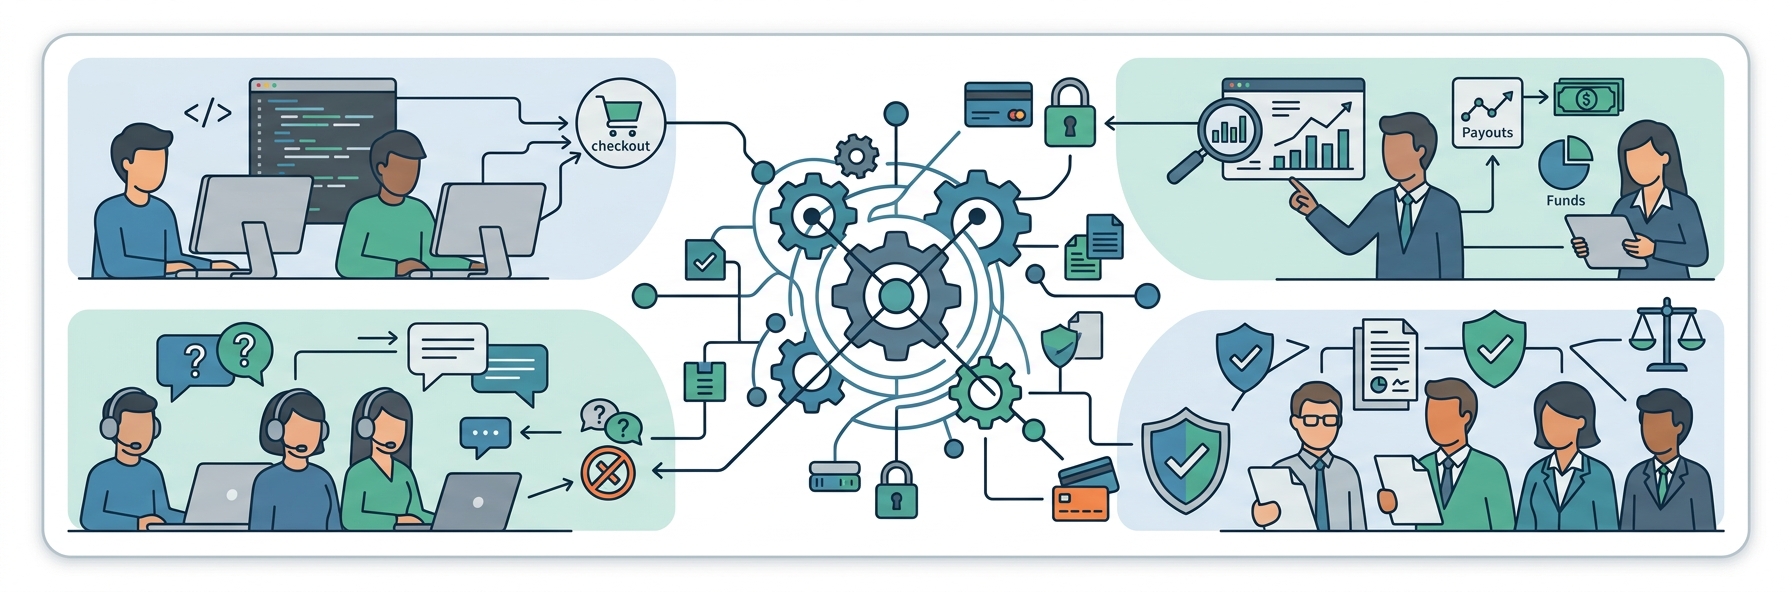
A payment system connects the work of developers, finance staff, and customer service. Developers integrate checkout, finance tracks payouts, and customer service answers questions about charges. For high-risk businesses, underwriting requirements and fraud exposure add complexity.
This review examines a specialist offering merchant account support, payment technology, and risk controls. Its appeal lies in helping businesses select processing arrangements suited to their operating requirements, with services that support implementation and ongoing payment management.
A Specialist Built Around Complex Payment Requirements
Adaptiv Payments focuses on businesses whose industries, transaction patterns, or business models require specialized processing arrangements. Its website identifies sectors such as travel, telehealth, nutraceuticals, subscriptions, and online retail.
The company evaluates each business’s industry, risk profile, and payment requirements, then considers suitable options through its banking and processing relationships. This consultative approach helps establish account suitability before a team commits development resources.
Its services include high-risk merchant accounts, gateways, ACH payments, virtual terminals, e-commerce integrations, fraud protection, and chargeback management. Approval depends on underwriting, and available capabilities vary with the selected arrangement.
How the Payment Infrastructure Fits Together
The gateway, processor, and merchant account perform distinct functions. The gateway captures payment information and submits transactions for authorization. The processor routes transactions through payment networks, while the merchant account receives funds from approved card transactions before payout to the business bank account.
The provider’s gateway page explains these components separately, giving technical and business stakeholders a common reference when discussing the proposed setup.
The e-commerce offering covers Shopify, WooCommerce, BigCommerce, and Adobe Commerce. Its integration page describes plugins, approved payment connections, and API options for custom stores. Teams should confirm the connection method for their platform and gateway.
Before rollout, developers should verify support for the required payment actions and test successful payments, declines, refunds, and order-status updates. This turns the provider’s integration options into a concrete validation plan.
Security Controls With Operational Value
The documented fraud tools include Address Verification Service (AVS), CVV checks, and 3D Secure. AVS compares submitted billing-address information with issuer records. CVV checks verify the card security code, while 3D Secure supports cardholder authentication.
The provider also describes real-time monitoring and controls against card testing. Teams should agree on which screening results trigger rejection, additional authentication, or manual review, and assign responsibility for reviewing flagged transactions and approving rule changes.
Tokenization replaces sensitive card information with a token in supported payment flows, limiting the use of raw card details. Fraud screening serves a separate purpose: assessing transaction risk. The 3-D Secure framework enables merchants and card issuers to exchange transaction and device information for cardholder authentication.
From Transaction Monitoring to Dispute Handling
The chargeback offering includes alerts, dispute-response assistance, Order Insight, and Rapid Dispute Resolution. The website explains how these tools act at different stages: supplying transaction details, enabling earlier intervention, or resolving eligible disputes through configured rules. This range is a strength for merchants needing both prevention and response support.
For an effective dispute workflow, customer service should investigate the customer’s concern, operations should check fulfillment records, and finance should confirm whether a refund has already been issued. Keep evidence in the appropriate business systems and use case references to coordinate the response. The provider supplies tools and assistance; the merchant manages its internal decisions and records.
Website Resources and Implementation Planning
The website organizes information by solution and industry, with a payments glossary, merchant category code resources, and FAQs. This structure helps technical buyers explore integration options and business owners assess whether the service addresses their needs.
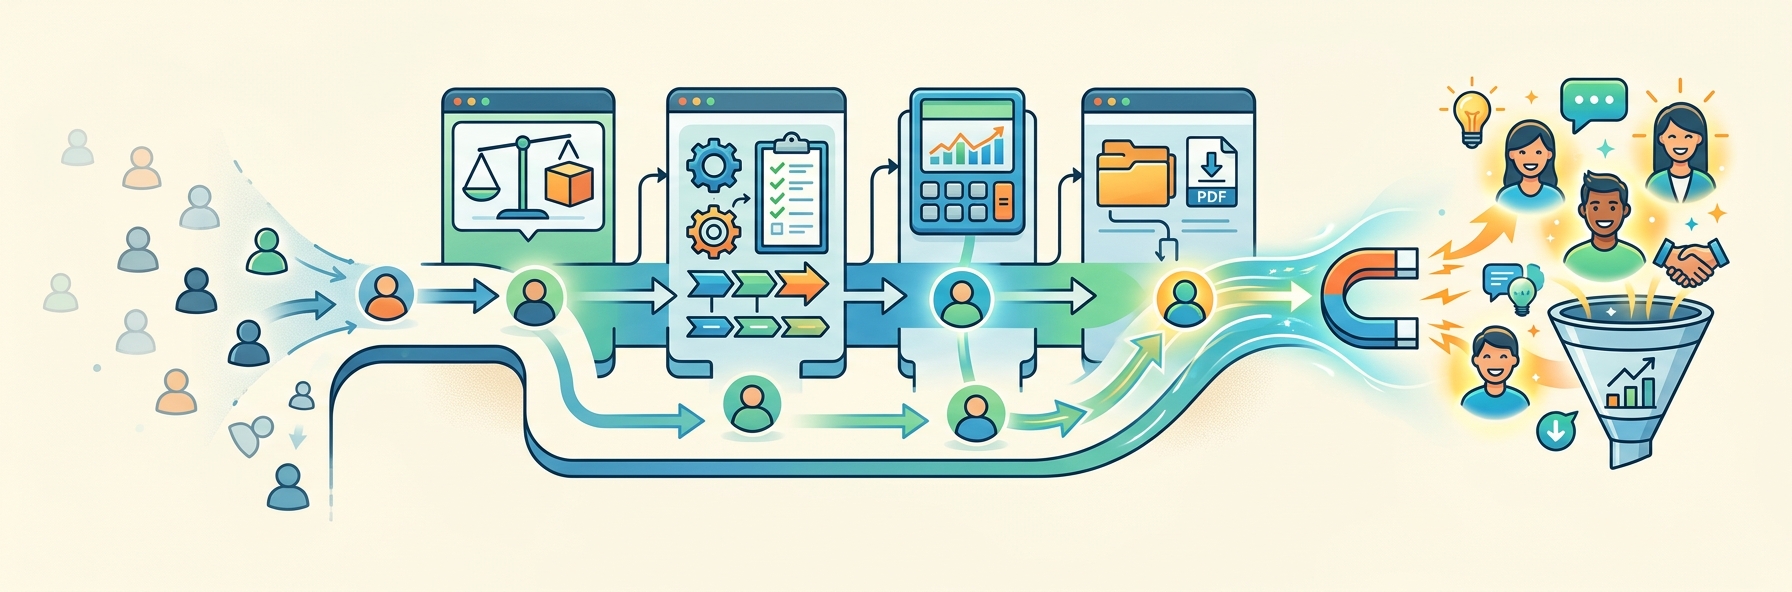
The application requests the business website, industry, current card acceptance, and processing volume. The company also describes assistance with configuring and activating approved services. These details give prospective merchants a clear starting point for preparing their application and discussing implementation.
A shared implementation plan should cover account documentation, gateway configuration, checkout testing, refund procedures, and escalation contacts. Effective team collaboration connects each task to an owner, deadline, and approval step.
Before launch, confirm processing fees, reserves, payout schedules, platform compatibility, and the included support arrangements. Record the agreed configuration and operating procedures so staff can refer to them when handling payment issues.
Final Assessment
For high-risk merchants seeking support from account selection through integration and dispute handling, the offering merits a close look. Its consultative approach gives teams a practical basis for planning payment operations. The final decision should rest on the capabilities and commercial terms included in the approved setup.
Published: October 7, 2026